What should a pest control invoice include?
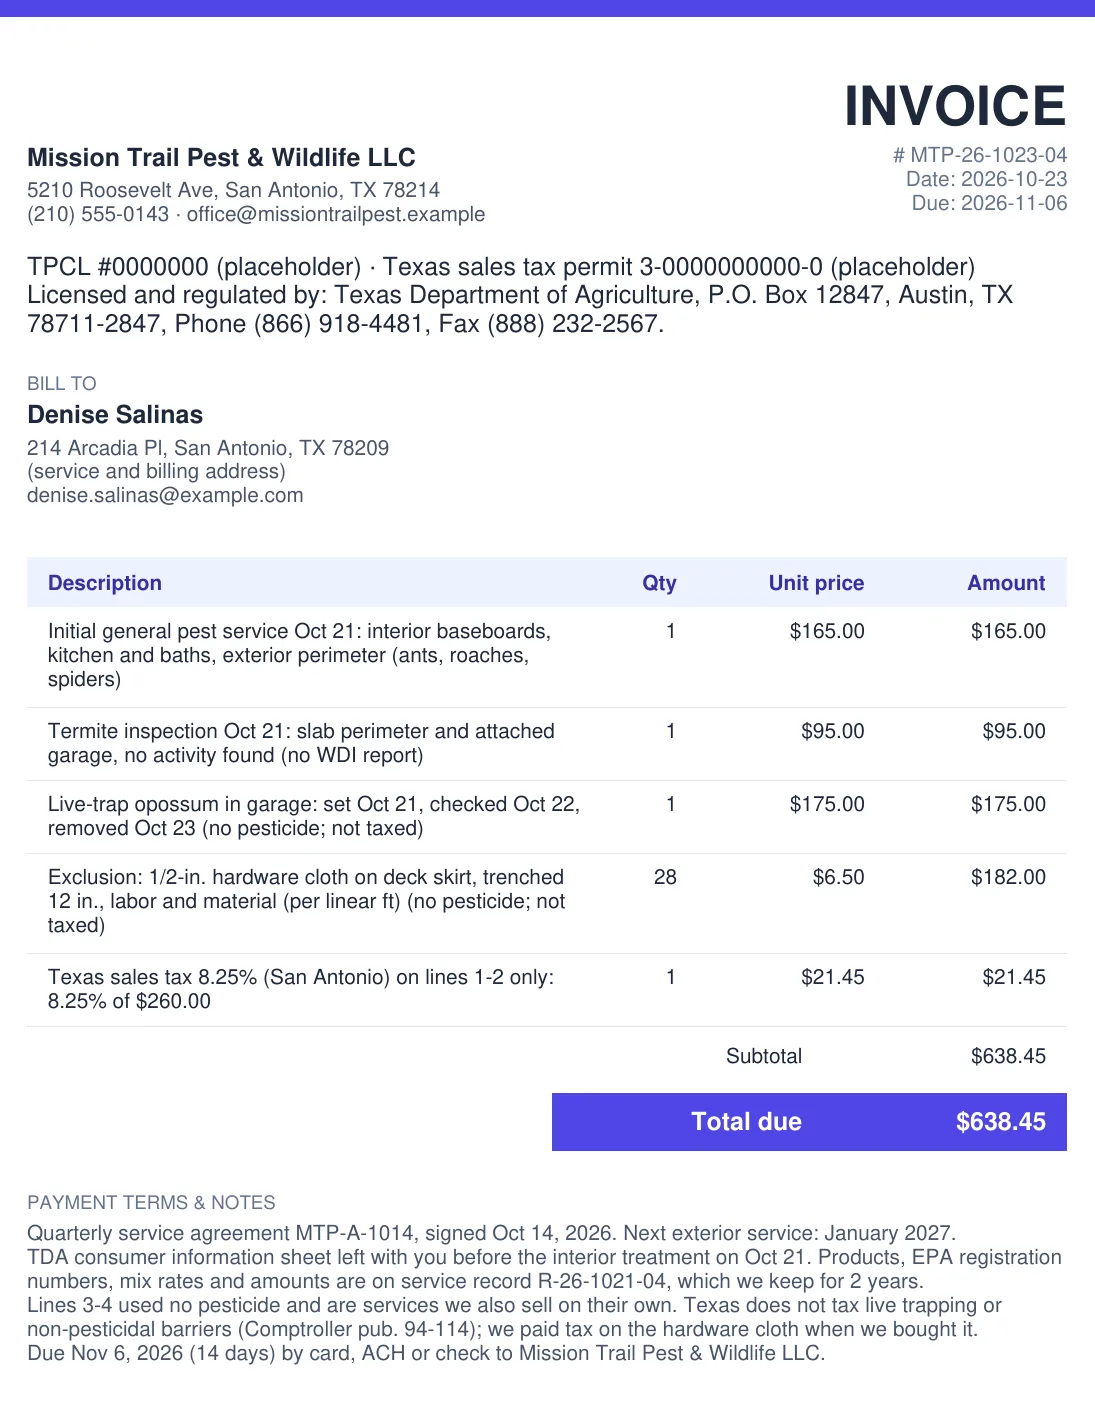
In Texas, start with what the Department of Agriculture puts on the face of every invoice: your business name, TDA business license number (and letter, if you have one), phone number, and physical or mailing address, in print at least 8-point. Then the customer, the service address, the invoice number and date, and one line per service with the date and what was done: general pest, termite inspection, trapping, exclusion. Keep taxable and untaxed services on separate lines, add the sales tax as its own line, then the total, the due date and how to pay. The example: $638.45 for one San Antonio house, $21.45 of it sales tax on the two taxable lines.
Line items pest control companies actually bill
- General pest service per visit, with the date and where you treated: interior, exterior perimeter, garage, attic.
- Inspections, termite or otherwise, even when nothing is found, with what you inspected.
- Termite treatment by the linear or square foot, or bait stations by the station.
- Rodent, wildlife and trapping work: trap sets and checks, removals, exclusion by the linear foot.
- Quarterly or monthly plan visits, naming the agreement and the period covered.
- Sales tax as its own line in Texas, worked out on the taxable lines only.
How the example adds up
| Part of the invoice | Unit | Amount |
|---|---|---|
| General pest service (taxable) | 1 visit × $165 | $165.00 |
| Termite inspection, nothing found (taxable) | 1 × $95 | $95.00 |
| Opossum live-trapped, no pesticide (not taxed) | 1 removal × $175 | $175.00 |
| Hardware-cloth exclusion, no pesticide (not taxed) | 28 linear ft × $6.50 | $182.00 |
| Texas sales tax, San Antonio 8.25% | 8.25% of ($165 + $95 = $260.00) | $21.45 |
| Total due | $165 + $95 + $175 + $182 + $21.45, by Nov 6 | $638.45 |
Tax on all four service lines would have been $50.90; billing the trapping and exclusion separately keeps $357.00 out of the tax base, which is what the Comptroller's publication allows for services that are distinct and commonly sold on their own. The company, the customer, the license and permit numbers and the prices are made up for the arithmetic.
In InvoiceSnap. The tax is a line of its own and Tax % stays at 0, because the form's tax field would tax every line. The TDA license number, the tax permit number and the jurisdiction statement go in the License field, which prints at 12 pt under your name; your address and phone print at 10 pt.
What TDA requires on the invoice
The Texas Department of Agriculture's Structural Pest Control Service rule for paperwork is 4 TAC §7.145, Contracts and Invoices. For invoices it is four items: "The business name, business license number (and letter if applicable), telephone number, and physical address or mailing address must be on the face of any invoice." They "must be legible and print shall be in at least 8-point type."
Contracts ask for more. "Each written contract, warranty, service agreement, termite disclosure document, or guarantee of a business regulated by the department must contain on the face of the document" the same business details plus this statement: "Licensed and regulated by: Texas Department of Agriculture, P.O. Box 12847, Austin, TX 78711-2847, Phone (866) 918-4481, Fax (888) 232-2567." The P.O. box, phone and fax match the SPCS contacts page today. The example is billed under a quarterly service agreement, so it repeats the statement on the invoice. The rule doesn't require that, and it doesn't hurt.
TDA's business license page also says a business can't advertise or solicit without a license, and: "A commercial business license fee is $300."
Texas sales tax on pest control
It is a taxable real property service. Tex. Tax Code §151.0048(a)(5) lists "a structural pest control service covered by Section 1951.003, Occupations Code". 34 TAC §3.356 defines structural pest control as work done "by use of chemical or mechanical means" against pests and says the term "includes related activities, such as inspection or evaluation concerning the nature or extent of an infestation; reports; or performance of services to control pest or insect infestation." Then: "Persons performing real property services must obtain a tax permit and collect and remit sales or use taxes on all charges for real property services."
What the Comptroller says to do. Publication 94-114, Pest Control Services (08/2021): "When you provide structural pest control services, you must collect sales tax from your customers (even when pests are not found)." "You should collect state and local sales tax on the total amount you charge for your pest control service, including any additional fees, even when pests are not found." "The tax rate is 6.25 percent state tax and up to 2 percent local tax." Local tax follows your place of business in Texas. San Antonio (Bexar County) adds 1.125% city, 0.375% ATD and 0.5% MTA, for 8.25% total in the Comptroller's city rate table.
What isn't taxed. The same publication lists, among others, "using a live trap to remove an animal from a residence, agricultural operation or business structure." and "installing, maintaining or using a non-pesticidal barrier to remove or prevent animal infestations." Those mirror Occupations Code §1951.058, which takes them out of TDA licensing "When performed without the use of a pesticide". For those jobs you are the consumer of what you use: "Nontaxable service providers must pay sales and use tax on all materials, supplies and equipment used in providing their services, including the chemicals used to perform the services." That is why the example's exclusion line includes the hardware cloth in one per-foot price and adds no tax to it.
Mixed invoices. "If your business performs both taxable and nontaxable services, your invoice must separately state the charges for the taxable and nontaxable services to your customer and you must collect tax on only the taxable service charges." "The nontaxable service must be distinct, identifiable, and a type of nontaxable service that you commonly provide by itself (i.e., not in combination with a taxable service)." If they are billed as one price: "If you do not bill your customer separately for the taxable service, and the charge for the taxable service represents more than 5 percent of the total price, you must collect tax on the entire charge." Travel and similar charges tied to the taxable work stay taxable: "Examples include charges for meals, calls, lodging and travel."
The paperwork that isn't the invoice
Treatment records. 4 TAC §7.144 requires records of every pesticide and device use "maintained for a period of two (2) years", with "the billing name and address of the customer", the service address, "names of pesticides and EPA registration numbers", amounts, mix rates, the target pest, the date and each applicator's name and license number. Termite treatments add the square feet treated per site. TDA can ask for them. The invoice doesn't have to repeat them, so the example names the record number.
Consumer information sheet. For an indoor treatment at an owner-occupied home, §1951.453(a) says the applicator or technician "shall make available a pest control information sheet developed under Section 1951.254 to the owner of the residence before each treatment begins." Rentals with five or more units, workplaces, schools, hospitals and similar buildings also need a pest control sign or notice 48 hours ahead (4 TAC §7.147), and "The department's consumer information sheet must be used."
Where the rules don't line up
- "Mechanical means" vs. live traps and barriers. Rule 3.356, last amended in 1995, defines structural pest control as pest work "by use of chemical or mechanical means", which on its face would cover a live trap or wire mesh. Publication 94-114 lists both as not taxable, matching §1951.058, which the Legislature added in 2009 and which applies only without a pesticide. The Tax Code ties the tax to a service "covered by Section 1951.003". The example follows the publication and the statute and says in the notes that no pesticide was used.
- Bees. The rule's definition lists "insects, spiders, mites, ticks, ants, bees, and other related pests"; the publication says "removing bees from a yard (it is not the removal of a pest or disease of trees; and it is not a structural pest control service, even if it is adjacent to a structure)." Bees in a wall or attic aren't addressed by that bullet. We treat those as an open question.
- Separately stated isn't always enough. In a 2017 private letter ruling on mosquito misting systems, the Comptroller said: "Taxpayer should collect tax on the total charge to the customer for a residential mosquito misting system, including any amounts charged for subsequent system maintenance or winterization, even if those amounts are separately stated." (STAR 201709011L.) Splitting lines only keeps a charge untaxed when the work itself is a distinct untaxed service, which is the publication's test too.
- The jurisdiction statement. §1951.451 requires "the department's mailing address and telephone number" and "a statement that the department has jurisdiction over individuals licensed under this chapter" on written contracts. Rule 7.145(a) gives the exact wording, including a fax number, and TDA's business page adds the "customer information sheet" to the documents it goes on, which the rule doesn't list. None of them asks for it on an invoice.
What we did not check
- Pest control sales tax in any state other than Texas.
- Texas rules for lawn and ornamental, weed control, fumigation and pre-construction termite categories beyond what is quoted here, and the Wood Destroying Insect Report form.
- Whether bee removal from a structure, or exclusion that includes a repellent, is taxable in Texas.
- Rule 3.291 (contractors) and how it treats materials on a separately priced exclusion job; the example uses one price for labor and material.
- Texas home solicitation (door-to-door) cancellation rules, which the consumer information sheet must mention.
- TDA penalties for missing invoice items, and typical prices; the example's are made up.
This is a summary of Tex. Tax Code §151.0048, Tex. Occ. Code chapter 1951, 34 TAC §3.356, 4 TAC §§7.144, 7.145 and 7.147, Texas Comptroller publication 94-114 and city rate table, STAR 201709011L and TDA's Structural Pest Control Service pages, as read on October 25, 2026, not legal or tax advice. Check with TDA (866) 918-4481, the Texas Comptroller, or your accountant.
Pool cleaning is a Texas real property service too. See the pool service invoice template for a worked monthly invoice with a repair.
Flea baths on the dog itself are taxed differently: the dog grooming invoice template shows a Fort Worth groomer taxing grooming and a flea shampoo while boarding stays untaxed.
FAQ
How do I make a pest control invoice?
Copy the services from the service ticket or agreement onto separate lines with the visit date in each description. Put the TDA business license number and your sales tax permit number in the License field so they print under your name; if the invoice doubles as the customer's copy of the agreement, add the TDA jurisdiction statement there too, as the example does. Work out the Texas sales tax on the taxable lines only and add it as its own line, leaving the Tax % field at 0. Put the agreement number, the consumer information sheet and where the treatment record is kept in the notes. In InvoiceSnap the totals update as you type and the free preview PDF shows the finished invoice.
Is pest control taxable in Texas?
Yes. The Tax Code's list of real property services includes "a structural pest control service covered by Section 1951.003, Occupations Code" (§151.0048(a)(5)), and 34 TAC §3.356(b) says "Persons performing real property services must obtain a tax permit and collect and remit sales or use taxes on all charges for real property services." The Comptroller's pest control publication: "When you provide structural pest control services, you must collect sales tax from your customers (even when pests are not found)." The rate is 6.25% state plus up to 2% local; San Antonio is at 8.25%.
Is a termite inspection taxable in Texas if no termites are found?
Yes. The Comptroller lists "the identification or inspection of infestations (or possible infestations)" as taxable and says to collect tax "on the total amount you charge for your pest control service, including any additional fees, even when pests are not found." The rule's definition of structural pest control includes "related activities, such as inspection or evaluation concerning the nature or extent of an infestation; reports; or performance of services to control pest or insect infestation." The example's $95 inspection found nothing and is taxed with the general pest service.
Which pest control services are not taxable in Texas?
The Comptroller's publication 94-114 lists services on timberland or for agricultural purposes, using a bird of prey to control birds, removing pests while cleaning a chimney, "removing bees from a yard", "using a live trap to remove an animal from a residence, agricultural operation or business structure.", mechanically removing weeds from a sewer, drain or lake, "installing, maintaining or using a non-pesticidal barrier to remove or prevent animal infestations.", and service bought as part of building a new home. Five of those match the Occupations Code's §1951.058, which takes them out of TDA licensing "When performed without the use of a pesticide". The example's opossum trapping and deck exclusion are on that list and used no pesticide.
Can I put taxable and non-taxable pest work on one invoice?
Yes, if they are separate lines. Publication 94-114: "If your business performs both taxable and nontaxable services, your invoice must separately state the charges for the taxable and nontaxable services to your customer and you must collect tax on only the taxable service charges." And: "The nontaxable service must be distinct, identifiable, and a type of nontaxable service that you commonly provide by itself (i.e., not in combination with a taxable service)." One price for a general pest service plus trapping is taxed in full if the pest part is more than 5% of it. That is why the example's notes say the trapping and exclusion are sold on their own.
Is a trip charge or service call fee taxable on a Texas pest control invoice?
Yes, when it is part of a taxable pest control service. The Comptroller: separately stated charges for services or expenses directly related to the pest control service "are taxable and may not be separated for the purpose of excluding these charges from the tax base. Examples include charges for meals, calls, lodging and travel." Rule 3.356(i)(3) says the same. If you add a trip charge to a general pest visit, put it in the taxable subtotal before working out the tax.
What does TDA require on a pest control invoice?
4 TAC §7.145(b): "The business name, business license number (and letter if applicable), telephone number, and physical address or mailing address must be on the face of any invoice." And §7.145(c): the information "must be legible and print shall be in at least 8-point type." InvoiceSnap prints your address at 10 pt and the License field at 12 pt, both above that minimum. The rule does not ask for the TDA jurisdiction statement on an invoice; that is for contracts and similar documents (next question).
What has to be on a Texas pest control contract or service agreement?
More than on the invoice. 4 TAC §7.145(a): "Each written contract, warranty, service agreement, termite disclosure document, or guarantee of a business regulated by the department must contain on the face of the document" the business name, license number, address and phone, and the jurisdiction statement: "Licensed and regulated by: Texas Department of Agriculture, P.O. Box 12847, Austin, TX 78711-2847, Phone (866) 918-4481, Fax (888) 232-2567." The statute behind it, Occupations Code §1951.451, asks for "the department's mailing address and telephone number" and "a statement that the department has jurisdiction over individuals licensed under this chapter". The example prints the statement on the invoice as well, which the rule doesn't require.
Do I need a license to do pest control in Texas?
Yes, for anyone in the business. Occupations Code §1951.301(b) says a person may not engage in the business of structural pest control without meeting TDA's standards and holding a structural pest control business license, one for each place of business, and §1951.003(a) counts inspections, "making oral or written inspection reports, recommendations, estimates, or bids" and treatments, whether you perform them, offer to or advertise them. TDA's business license page: "A commercial business license fee is $300." The business must also employ a certified commercial applicator at all times (§1951.301(e)).
What is the Texas pest control consumer information sheet?
A TDA form you must make available before indoor treatments. Occupations Code §1951.453(a): for an indoor treatment at a private residence that is not rental property, the applicator or technician "shall make available a pest control information sheet developed under Section 1951.254 to the owner of the residence before each treatment begins." Rentals, workplaces, schools and similar buildings have their own notice and sign rules (§§1951.453-1951.455, 4 TAC §7.147), and "The department's consumer information sheet must be used." (§7.147(f)). The example's notes say when it was left, so the invoice and the record agree.
Does the invoice count as the pesticide treatment record?
No. 4 TAC §7.144 requires a separate use record kept for two years at the business, with "the billing name and address of the customer", the service address, "names of pesticides and EPA registration numbers", amounts, mix rates, the target pest, the date, and the name and license number of each applicator; termite jobs add square feet treated and more. Some companies print that on the service ticket. The example keeps the invoice short and names the record number in the notes instead of listing products it can't verify for you.
Is mosquito misting taxable in Texas?
The Comptroller says yes when you sell and install the system or add pesticide to it. A 2017 private letter ruling to a licensed company: "Taxpayer should collect tax on the total charge to the customer for a residential mosquito misting system, including any amounts charged for subsequent system maintenance or winterization, even if those amounts are separately stated." Repairing someone else's system with no pesticide work is different: "When residential repair and maintenance is sold on a stand-alone basis, without the provision of a structural pest control service, it is not taxable." It is one taxpayer's ruling on its facts.
Is pest control taxable in Florida, Wisconsin or other states?
We did not check other states for this page. Search suggestions show people asking about Florida, Wisconsin, Kentucky, Louisiana, Pennsylvania, California, Indiana and Maryland; each state sets its own rules. The worked example and every rule quoted here are Texas.
Can I use this for termite, rodent, bed bug or quarterly service invoices?
Yes. Use one line per visit or treatment with the date and the target pest, and the unit you priced in: per visit for a quarterly service, per square foot or linear foot for termite work, per trap check or per device for rodents, per room or per unit for bed bugs. In Texas, inspections and treatments for any of those are taxable; the exceptions are the ones listed above, such as live trapping and non-pesticidal exclusion done without a pesticide. For a termite report used in a home sale, TDA prescribes its own Wood Destroying Insect Report form; we did not review that form for this page.
Is InvoiceSnap free?
Yes. You can fill in the invoice and download a watermarked preview PDF free with no signup. A clean PDF is $4 one-time for 7 days of unlimited invoices (USDC; card coming soon).
Is my data uploaded?
No. The PDF is generated in your browser; your client and pricing details are not sent to a server.
More invoice templates
Freelance invoice template (fill online → PDF) · Independent contractor invoice template · Hourly invoice template (hours worked) · Consulting invoice template · Invoice with a discount line · Invoice template for international clients · Photography invoice template · Cleaning invoice template · Landscaping & lawn care invoice template · Plumbing invoice template · Electrician invoice template · HVAC invoice template · Roofing invoice template · Painting invoice template · Handyman invoice template · Deposit invoice template · Videographer invoice template · DJ invoice template · Tutoring invoice template · Lawn care invoice template · Late fee invoice template · Auto repair invoice template · Catering invoice template · Moving invoice template · Trucking invoice template · Web design invoice template · Translation invoice template · Graphic design invoice template · Snow removal invoice template · Pool service invoice template · Pressure washing invoice template · Window cleaning invoice template · Junk removal invoice template · Carpet cleaning invoice template · Dog grooming invoice template · Pet sitting invoice template · InvoiceSnap home